Personal Finance Made Easy: A Guide to Money Basics
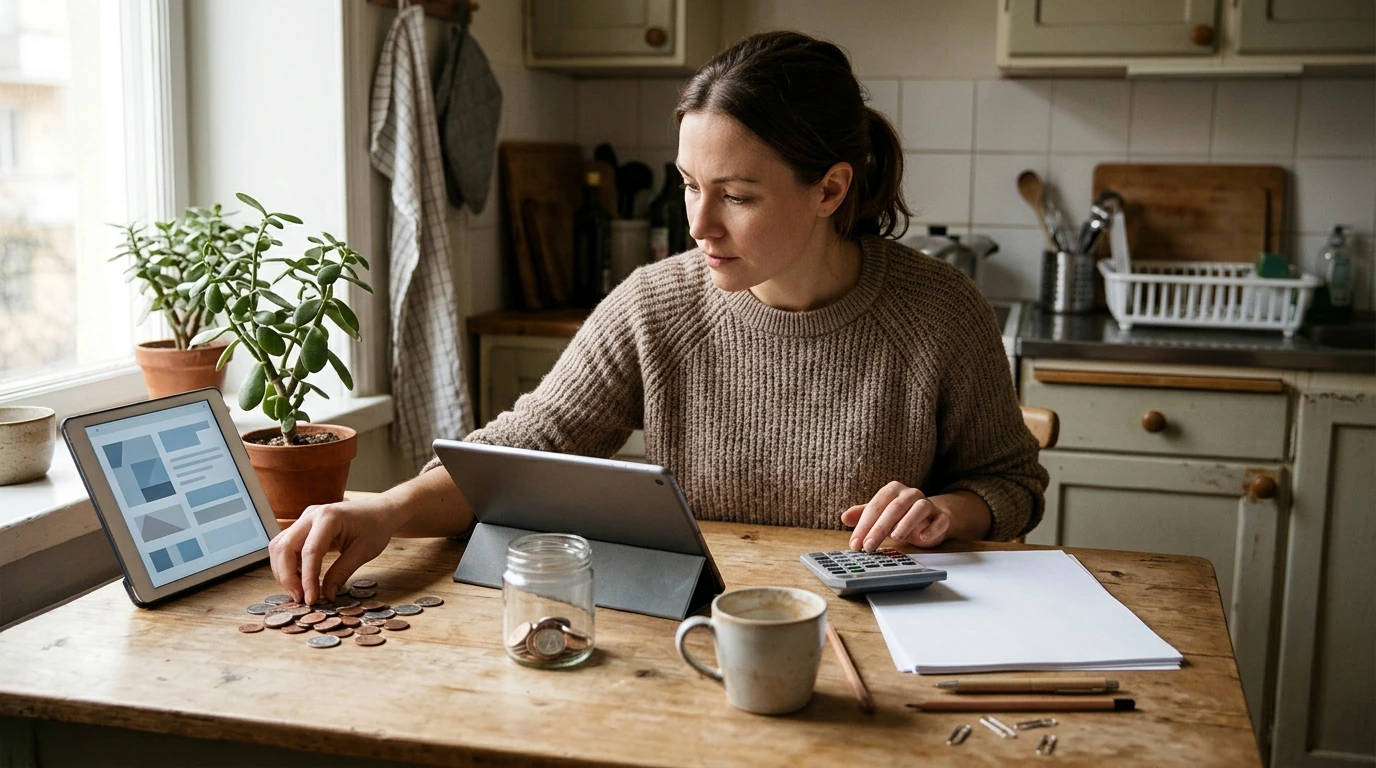
Financial freedom can mean different things to different people: more room in your monthly budget, fewer debts, or greater confidence about the future. Whatever your goal, a useful starting point is understanding how budgeting, saving, investing, and debt management connect.
Our Personal Finance Made Easy ebook brings these four topics together as an introduction to managing your money. It can help you organize your learning, but your financial results will depend on your circumstances and decisions—not on any guaranteed formula.
Start With a Clear Picture of Your Money
Before deciding what to change, take stock of what comes in and what goes out each month. Start with your take-home income, then list essential expenses such as housing, utilities, groceries, and insurance. Add flexible spending, including entertainment and dining out, along with required debt payments.
If your income varies, consider reviewing several months to get a more representative picture. You can also note expenses that don’t occur monthly, such as annual fees or car maintenance, so they don’t catch you off guard.
A simple budget doesn’t need to follow a universal percentage rule. Its purpose is to show whether your income covers your commitments and where adjustments may be possible. You might find room to reduce a subscription, plan meals differently, or set aside a small amount for an upcoming bill. If your essentials exceed your income, the priority may be finding support or reviewing larger expenses rather than trimming minor purchases.
The Consumer Financial Protection Bureau’s Your Money, Your Goals resources offer additional tools for tracking expenses and making a plan.
Build Savings Into Your Plan
Choose a savings amount that fits your current budget, even if it’s modest. You could set aside a fixed dollar amount after each paycheck or transfer whatever remains after necessary expenses. The important decision is choosing an approach you can revisit as your income, bills, and priorities change.
An emergency fund can provide a buffer for unexpected costs, such as a medical bill or urgent repair. There is no single target that suits everyone: your income stability, household needs, insurance coverage, and other resources all matter. Consider keeping this money somewhere accessible so you can use it when needed.
Separate savings goals can also make planning clearer. For example, money for an upcoming holiday expense serves a different purpose from money reserved for an emergency. Naming each goal can help you decide how much to contribute and when you may need it.
Balance Debt Payments and Investing
Start your debt plan by listing each balance, interest rate, and minimum payment. Making required minimum payments is an important consideration when comparing repayment approaches. Beyond that, you might focus extra payments on a high-interest balance to reduce interest costs, or choose another approach that fits your circumstances and helps you stay consistent.
Saving and debt repayment don’t always have to be an either-or choice. A small emergency buffer may help you handle an unexpected expense without adding to debt, while higher interest rates may make extra debt payments especially valuable. Your available cash flow and obligations will shape the balance.
Investing is generally a longer-term activity, and investments can lose value. Unlike emergency savings, invested money may not be readily available at the value you expect when an urgent expense arises. Consider your goals, time horizon, and comfort with risk before investing. For a closer look at the basics, explore Investor.gov’s introduction to investing.
Four Areas of a Personal Finance Plan
| Area | Starting action | Purpose |
|---|---|---|
| Budgeting | List income and expenses | Understand available cash flow |
| Saving | Set aside an affordable amount | Prepare for goals and unexpected costs |
| Debt management | List balances, rates, and minimum payments | Choose a repayment approach |
| Investing | Consider goals, time horizon, and risk | Plan for longer-term needs |
These areas work together: a budget shows what may be available, savings can help cover surprises, and a debt plan can inform how much you can direct toward longer-term goals.
Who Might Find the Ebook Useful?
Our ebook is for readers who want an introduction to several personal finance topics in one place. You may find it useful if you’re building your first budget or want to revisit how your savings, debt, and investing decisions relate to one another.
General information is a starting point, not a substitute for advice tailored to you. Adapt what you learn to your finances, and consider a qualified financial, tax, or credit professional when you need help with a specific decision.
Explore Personal Finance Made Easy
Personal Finance Made Easy is an in-stock digital product priced at $20.99 USD. Visit the product page to decide whether it fits your financial learning goals.
Planning for individual occasions can be part of a broader budget, too. If you’re organizing a celebration, our in-stock Party Invitation Checklist is a separate resource priced at $6.99 USD. Consider its cost alongside the other expenses in your plan.
FAQ
What topics does Personal Finance Made Easy cover?
The ebook introduces budgeting, saving, investing, and debt management.
Should I save money or pay off debt first?
The right balance depends on your emergency savings, debt interest rates, minimum payment obligations, and other circumstances. You may choose to work on savings and debt payments at the same time.
Does the ebook guarantee financial freedom?
No. Financial outcomes depend on your individual circumstances and decisions.


Leave a comment